Navigating family finances involves more than just numbers on a spreadsheet. It blends money with relationships, emotions, and long-term goals. Whether you are creating a joint budget, planning for college tuition, or separating assets, these conversations are often difficult.
Establishing a clear process can remove much of the stress and uncertainty, allowing you to focus on making sound, logical choices for everyone involved. The key is to approach it methodically, one step at a time.
Understanding Your Financial Landscape
Before you can make any decisions, you need a complete and honest picture of your collective finances. Start by listing all sources of income, including salaries, bonuses, and any freelance or investment earnings. Next, compile a list of all your assets. This includes cash in checking and savings accounts, retirement funds like 401(k)s and IRAs, investment portfolios, real estate, and valuable personal property.
At the same time, create an equally detailed list of all your liabilities. This should cover mortgages, car loans, student loans, credit card balances, and any other personal debts. Having this complete overview provides a clear, factual baseline for all future discussions.

Identifying Shared Assets and Debts
One of the most complex parts of managing family money is distinguishing between what is shared and what is separate. Shared, or "community," assets are typically items acquired through a partnership. For example, a home purchased together is a shared asset, as is the debt from a joint credit card.
Untangling these finances becomes particularly critical during major life changes. Dividing property during a divorce, for instance, requires a meticulous separation of joint and separate property to ensure a fair outcome. This same principle applies when creating prenuptial agreements or estate plans, where clearly defining ownership prevents future confusion and conflict.
Valuing Complex Investments and Businesses
While it’s easy to determine the value of a savings account, some assets are much harder to quantify. These can include a family-owned business, stock options, pensions, or unique collectibles. These types of investments don't have a simple price tag, and their value can fluctuate based on market conditions, business performance, or vesting schedules.
For these complex assets, a simple estimate isn't enough. You often need a professional valuation to determine their true worth. An appraiser or a forensic accountant can analyze the business's financials or the pension's terms to provide an objective and defensible figure. This step is crucial for ensuring that decisions are based on accurate information, not guesswork. Without a proper valuation, one party could be left at a significant financial disadvantage.
Planning for Future Financial Stability
Making financial decisions isn't just about dividing what you have now. It's also about setting each person up for future success. Once assets and debts are understood, the focus should shift to long-term planning. This involves creating new, individual budgets based on projected income and expenses. It’s an opportunity to set fresh financial goals, whether that’s saving for a down payment on a new home, paying down debt, or rebuilding a retirement fund.
A comprehensive financial planning guide can offer a roadmap for this process. It helps you consider factors like health insurance costs, tax implications, and how to adjust your investment strategy to align with your new circumstances. Taking the time to build a solid plan provides a sense of control and security for the years ahead.
Seeking Professional Financial Guidance
You do not have to handle these complex financial decisions on your own. In fact, seeking outside help is often the wisest course of action. Emotions can run high during family financial discussions, and an objective third party can provide clarity and direction. A financial advisor can help you create a sustainable budget and investment plan for your new life, guiding you to make sensible financial decisions this year. An accountant can explain the tax consequences of different asset division scenarios.
Bringing in professionals helps maintain civility and ensures the process remains productive. It's also a way of setting financial boundaries that protect your interests while keeping discussions focused on facts rather than feelings. Their expertise can help you avoid common pitfalls and move forward with confidence.
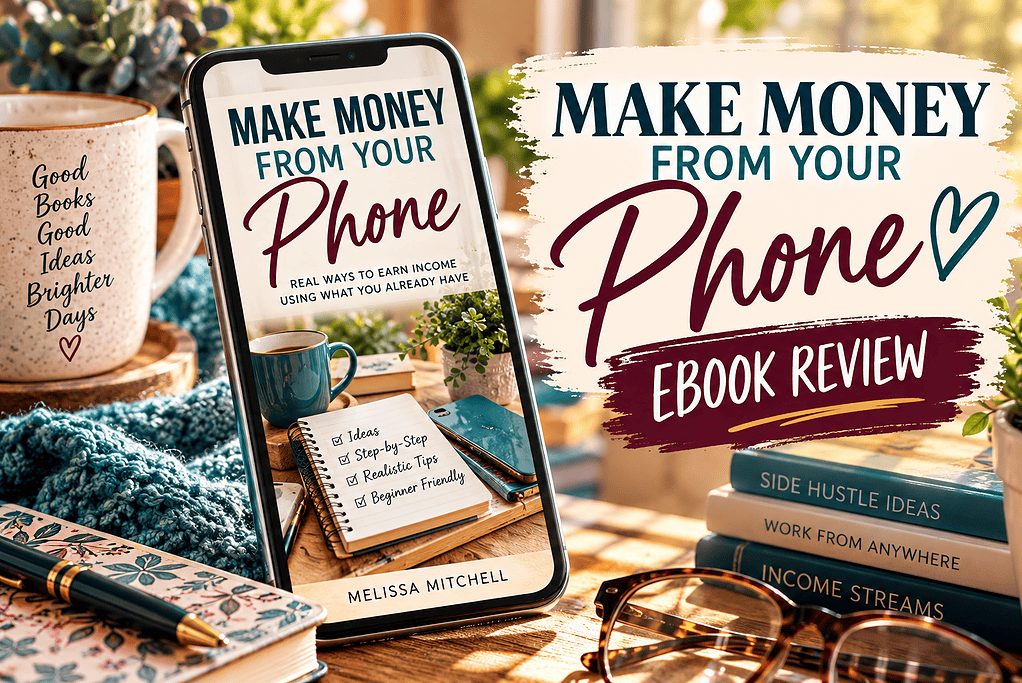
How to Make Money From Your Phone Book: Is It Worth Reading?
How to Take Control of Your Finances With Smart Financial Planning
Making Difficult Decisions About Family Finances
How Trustworthy Systems Impact Peace of Mind
What Do You Need To Get A Mortage In The Modern World?

How BC Stack 2026 Is Helping Me Turn a Lifelong Dream Into Reality
I’m especially excited about BC Stack 2026 because this year feels completely different for me....